Asset Purchase vs Share Purchase: Choosing the Right Deal
When a buyer decides to acquire a business, one of the first questions is simple: what exactly should be acquired?
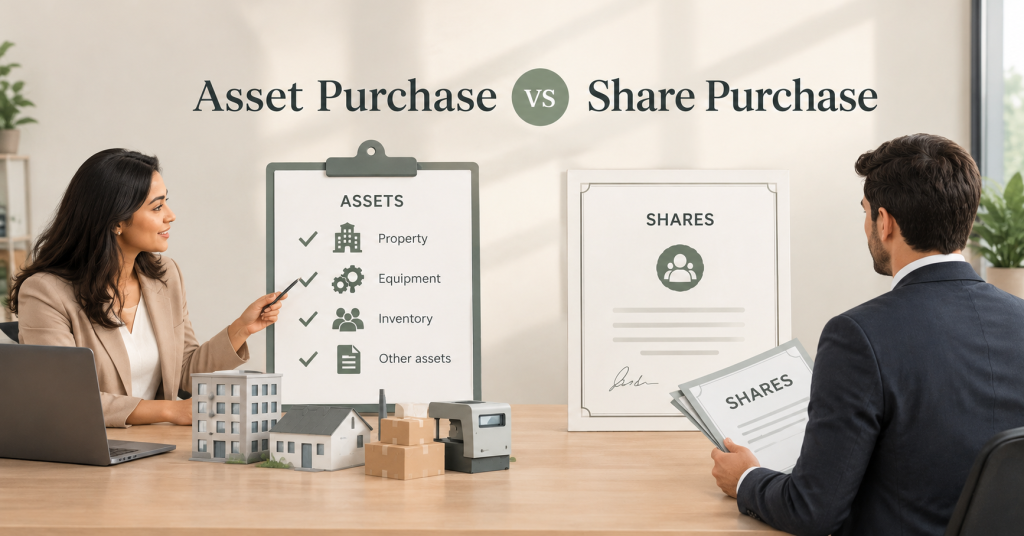
The buyer could purchase the shares of the target company or acquire specific assets or a defined business from it. This choice is known as asset purchase vs share purchase, and it can affect liabilities, contracts, employees, approvals, due diligence and the way the transaction is completed.
If you are new to M&A, start with DealCraft Academy’s What Is M&A? A Beginner’s Guide to Mergers and Acquisitions for the broader framework.
What Is an Asset Purchase?
An asset purchase is an M&A transaction where the buyer acquires specific assets or a defined business from the seller rather than purchasing the seller’s shares.
The assets could include:
- Intellectual property and technology
- Machinery and equipment
- Inventory
- Real estate
- Customer contracts
- A particular business division or undertaking
The transaction documents identify what is being acquired and, subject to applicable law and the agreed terms, which liabilities the buyer will assume.
Example:
Suppose Company A wants Company B’s software business but not its unrelated manufacturing division or certain historical liabilities. An asset deal could allow Company A to acquire the specified software assets and business operations instead of buying Company B itself.
What Is a Share Purchase?
A share purchase is an M&A transaction where the buyer acquires shares in the target company from its existing shareholders.
The target company continues to exist as the same legal entity. Its assets, contracts, employees and liabilities generally remain with that company. What changes is who owns and controls it.
Key points include:
- The buyer acquires shares rather than individual assets.
- The target’s existing business continues through the same entity.
- Existing liabilities remain within the target company.
- Existing contracts and licences may continue, although change-of-control provisions can still require consent.
- Due diligence becomes particularly important because the buyer is acquiring the company with its existing history and exposures.
Example:
If Company A purchases 100% of Company B’s shares, Company B still owns its factory, IP, contracts and other assets. Company A now controls Company B through its ownership of the shares.
Asset Purchase vs Share Purchase: What’s the Difference?
| Key Factor | Asset Purchase | Share Purchase |
|---|---|---|
| What is acquired? | Selected assets or business | Shares in the target company |
| Who owns the assets? | Buyer after transfer | Target company continues to own them |
| Liabilities | Determined by the transaction and applicable law | Remain with the target company |
| Contracts | May require assignment or consent | Usually remain with the target, subject to change-of-control provisions |
| Corporate entity | Seller’s company generally remains with the seller | Target continues under new ownership |
| Key buyer concern | What is being transferred and what is being assumed? | What liabilities and risks exist within the target? |
The difference is therefore not simply “assets versus shares.” It is about the perimeter of the acquisition: what comes into the buyer’s hands, what stays with the seller and what risks travel with the transaction.
The Same Business Can Lead to Two Different Deals
Consider a technology company that owns valuable software, customer contracts and intellectual property, but also has an old manufacturing division and an ongoing dispute.
If the buyer only wants the technology business, an asset purchase may be considered because the buyer can identify the assets and business it wants to acquire, subject to transferability and applicable law.
If the buyer wants the entire operating company, a share purchase may make more sense. The buyer acquires the company that already holds the contracts, employees, IP and other assets.
This is why the right M&A deal structure cannot be selected simply by asking which option is “better.” The buyer’s commercial objective comes first.
What Happens to Liabilities?
Liability exposure is one of the biggest differences between an asset deal and a share deal.
In an asset purchase, the parties can define the liabilities that the buyer will assume, but the actual position depends on the transaction documents and applicable law. Some liabilities may also follow particular assets or businesses by operation of law.
In a share purchase, the target company remains responsible for its existing liabilities because the same legal entity continues after the acquisition. From the buyer’s perspective, this means historical tax issues, litigation, contractual obligations or other undisclosed exposures can remain relevant to the investment.
That is why warranties, indemnities and thorough due diligence are particularly important in a share acquisition.
Contracts, Employees and Licences Matter Too
- In an asset purchase, individual contracts, leases, licences or other rights may need assignment, novation, fresh documentation or third-party consent.
- In a share purchase, contracts generally remain with the target because the legal entity itself has not changed. However, a change-of-control clause in the contract may still require the buyer to obtain consent or meet certain conditions.
Employees and key business relationships also need to be considered carefully because the treatment can differ depending on what is actually being transferred. For a broader look at how contracts, cash and control are affected during an acquisition, see How Does an Acquisition Work? Control, Cash and Contracts.
How Does Due Diligence Affect the Choice?
Due diligence can change the preferred acquisition structure.
Suppose a buyer initially plans a share purchase but discovers significant historical tax exposure, litigation or regulatory issues during diligence. The buyer may negotiate additional protections, reconsider the price or explore another structure.
Similarly, an asset deal may look attractive until the buyer discovers that important customer contracts or licences cannot easily be transferred.
This is why acquisition structure and due diligence should not be treated as separate exercises. The findings from diligence can directly influence how the deal is ultimately structured.
SPA or Asset Purchase Agreement?
The documentation generally follows the structure.
A Share Purchase Agreement (SPA) is used when shares in the target company are being transferred.
An Asset Purchase Agreement or, depending on the transaction, a Business Transfer Agreement (BTA) may be used when assets or a business undertaking are being transferred.
The agreement then sets out the commercial terms, conditions, representations, warranties, indemnities and closing requirements relevant to that structure.
Which Structure Should a Buyer Choose?
There is no universal answer.
An asset purchase may be considered when:
- The buyer wants only selected assets or a specific business.
- The seller operates multiple unrelated businesses.
- The buyer wants greater control over which liabilities it assumes.
- Particular assets are more valuable to the buyer than the entire corporate entity.
A share purchase may be considered when:
- The buyer wants the entire operating company.
- Existing contracts and business relationships are important.
- Continuity through the existing corporate entity is commercially valuable.
- The target has a manageable risk profile following due diligence.
The final choice can also depend on tax, regulatory, financing, commercial and transaction-specific considerations.
Choosing the Right Deal Structure
The real question in an acquisition is not simply “Should I buy assets or shares?”
It is:
What does the buyer actually need to acquire, what risks is it prepared to take, and what is the most practical way to transfer the business?
Once those questions are clear, the choice between an asset deal and a share deal becomes much easier to analyse.
For anyone building a foundation in M&A terminology and deal structures, DealCraft Academy’s First Year Associate’s Deal Vocabulary is a useful starting point. For a more structured understanding of M&A transaction structures and core deal documents, explore Master M&A Fundamentals.
Frequently Asked Questions
What is the difference between an asset purchase and a share purchase?
An asset purchase involves acquiring specified assets or a business, while a share purchase involves acquiring ownership of the target company through its shares.
Is an asset purchase better for a buyer?
Not always. An asset purchase can provide greater control over what is acquired and which liabilities are assumed, but transferring individual assets, contracts and licences can make the transaction more complex.
What liabilities transfer in an asset purchase?
The buyer generally assumes the liabilities specifically agreed to in the transaction, subject to applicable law. Certain liabilities may also transfer by operation of law, so the transaction requires careful legal and tax analysis.
What happens to liabilities in a share purchase?
The target company continues to hold its liabilities because the same legal entity continues after the share transfer. The buyer therefore needs to understand the target’s historical and potential liabilities before acquiring its shares.
Do contracts transfer in an asset purchase?
Not automatically in every case. Contracts may require assignment, novation or third-party consent. The specific contract terms and applicable law need to be reviewed.
Is a share purchase easier than an asset purchase?
A share purchase can be operationally simpler where the target’s existing corporate structure, contracts and licences are important. However, it can require extensive due diligence because the buyer acquires the target with its existing history and liabilities.
What is the difference between an SPA and a BTA?
An SPA is generally used for the purchase of shares in a company. A BTA is generally used to document the transfer of a business or undertaking. The appropriate agreement depends on the transaction structure and what is being transferred.
How should a buyer decide between an asset deal and a share deal?
The buyer should consider what it wants to acquire, which liabilities it is prepared to assume, whether contracts and licences can be transferred, the target’s risk profile, tax and regulatory implications, and the practical requirements for closing.
Recent Comments